Article from the DRAAYV blog · published on 06/03/2025
Historical text used for this preview. The trends and general information do not constitute the current contractual conditions of DRAAYV.
Revision to be carried out before publication
Revise before publication: coverage presented as usual/included, example of excess, advice on unsealed roads and bank card guarantees. Do not present this text as the DRAAYV guarantees. The waiver without deposit requires a dedicated explanation.
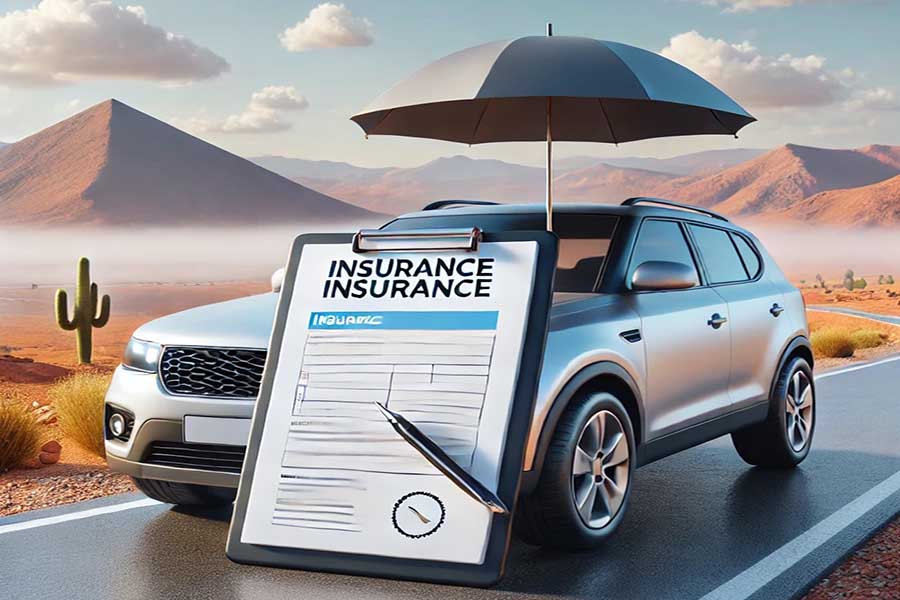
Renting a car offers great freedom when traveling, but it is crucial to understand the insurance options available to avoid unpleasant surprises. Between basic guarantees, deductibles and additional options, here's everything you need to know before signing your rental contract.
Back to blog Insurance included in car rental
When you rent a vehicle, certain insurance is often included by default in the rental price. Here are the main guarantees:- Civil liability insurance (TPL - Third Party Liability): Mandatory, it covers damage caused to third parties in the event of an accident.
- CDW (Collision Damage Waiver) insurance: It limits your liability in the event of damage to the rented vehicle, but often includes a deductible.
- Theft Protection (TP) insurance: It covers the loss or theft of the vehicle, but it may also involve a deductible.
Additional insurance options
To avoid high costs in the event of a disaster, rental agencies offer several additional insurance policies:- All-risk insurance without deductible: It allows you to eliminate the deductible in the event of an accident.
- Window and tire breakage insurance: Useful because these elements are not always covered by basic insurance.
- Road assistance insurance: It covers breakdown assistance and towing in the event of breakdowns or punctures.
- Driver and passenger insurance: It covers medical costs in the event of an accident.
How does the franchise work?
The excess is the amount that remains your responsibility in the event of an accident or theft of the vehicle.- Example: If the deductible is €1,000 and the damage costs €3,000, you will have to pay the €1,000, and the insurance will cover the rest.
- The lower the deductible, the higher the cost of insurance.
- Certain bank card insurance policies can reimburse the excess, check your banking contract before taking out additional insurance.
Should I take out additional insurance?
This depends on several factors:- Your risk tolerance: Comprehensive insurance avoids stress in the event of the unexpected.
- The planned route: If you drive in town, the risk of collision is higher.
- The condition of the roads: On unpaved roads, broken glass and tire insurance can be useful.
- Your bank card: Some already cover the excess, find out more.
- Tips for choosing your rental insurance
- Read the contract carefully: Identify what is included and the exclusions.
- Compare offers: Some companies offer more advantageous packages.
- Check your bank card guarantees: Many include rental coverage.
- Carry out a careful inventory: Take photos before and after the rental to avoid disputes.